


FHA 203k Loan Providers: Your Guide to Renovation Financing

Buying a home that needs some work? You might feel overwhelmed by the idea of juggling a mortgage and renovation costs separately. That’s where the FHA 203k loan steps in. It’s a smart way to finance both your home purchase and the repairs or improvements you want to make. If you’re curious about how to find the right lenders and what to expect, you’re in the right place. Let’s dive into the world of FHA 203k loans and explore how they can help you turn a fixer-upper into your dream home.
Understanding FHA 203k Loan Providers
When it comes to FHA 203k loans, not every lender offers this specialized product. These loans require a bit more paperwork and expertise because they combine home buying and renovation financing into one package. So, how do you find the right FHA 203k loan providers?
First, look for lenders who have experience with renovation loans. They understand the unique process, including the appraisal and contractor approval steps. Many traditional mortgage lenders offer FHA 203k loans, but some specialize in them. You can start by checking with local banks, credit unions, or mortgage brokers who serve your area.
Here are some tips to help you choose the best lender:
Ask about their FHA 203k loan experience. How many loans have they closed? What types of renovations do they typically finance?
Check their turnaround times. Renovation loans can take longer to process, so find out how quickly they move.
Understand their contractor requirements. Some lenders have a list of approved contractors or require detailed bids.
Compare interest rates and fees. Even small differences can add up over time.
Remember, a good lender will guide you through the process, answer your questions, and help you avoid surprises.

How FHA 203k Loans Work: A Simple Breakdown
The FHA 203k loan is designed to help you buy a home that needs repairs or improvements. Instead of getting a separate loan for the renovation, you get one loan that covers both the purchase price and the cost of repairs.
Here’s how it works:
Find a home that needs work. This could be a fixer-upper or a property that requires updates.
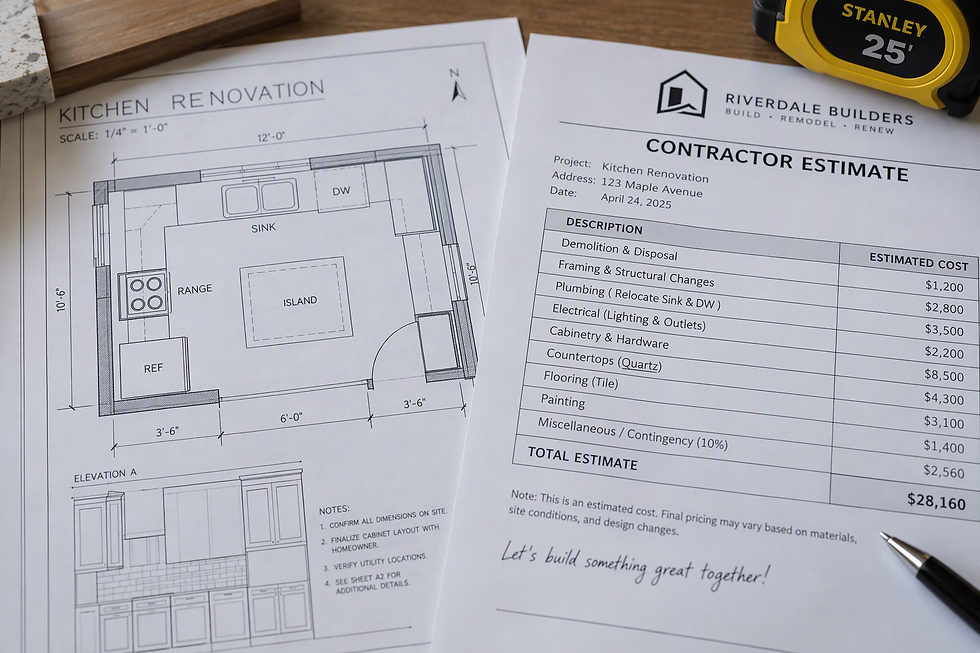
Get a contractor’s estimate. You’ll need a detailed list of repairs and costs.
Apply for the FHA 203k loan. Your lender will review your application, the property, and the renovation plan.
Loan approval and closing. The loan amount includes the purchase price plus renovation costs.
Renovation phase. Funds for repairs are held in escrow and released as work is completed.
Final inspection. Once renovations are done, the lender verifies the work.
This loan is great because it lets you finance everything in one mortgage, often with a low down payment. Plus, FHA loans tend to have more flexible credit requirements.
If you’re wondering about the types of repairs allowed, they range from minor fixes like painting and flooring to major structural work. However, luxury upgrades or additions usually aren’t covered.
Can a 70 Year Old Woman Get a 30 Year Mortgage?
Age can sometimes feel like a barrier when applying for a mortgage, but here’s the good news: Yes, a 70 year old woman can get a 30 year mortgage. Lenders focus more on your income, credit score, and ability to repay the loan than your age.
With FHA loans, including the 203k, there’s no maximum age limit. The key is proving you have steady income or assets to cover payments. For seniors, this might include retirement income, Social Security, or pensions.
If you’re concerned about long-term payments, you might also explore options like reverse mortgages, but those are different from FHA 203k loans. The 203k loan is ideal if you want to buy and renovate a home with a traditional mortgage structure.
Here are some tips if you’re a senior applying for a 30 year mortgage:
Gather proof of income and assets. This helps reassure lenders.
Maintain a good credit score. It improves your chances and loan terms.
Consider your long-term plans. Make sure the mortgage fits your financial goals.
Work with a lender experienced in senior financing. They can offer personalized advice.
Age doesn’t have to limit your homeownership dreams, especially with flexible FHA loan options.
What to Expect When Working with FHA 203k Renovation Loan Lenders
Navigating the FHA 203k loan process can feel complex, but knowing what to expect makes it easier. When you work with fha 203k renovation loan lenders, you’ll find they handle a lot of the heavy lifting.
Here’s a typical journey:
Pre-approval: The lender reviews your financials and credit.
Home selection: You find a property that qualifies for the 203k loan.
Renovation plan: You submit contractor bids and a detailed scope of work.
Loan processing: The lender orders an appraisal that includes the home’s “as-is” and “after repair” values.
Closing: You sign paperwork for the combined loan.
Renovation phase: Funds are disbursed in draws as work progresses.
Final inspection: The lender confirms the work is complete and meets FHA standards.
Throughout this process, communication is key. Your lender should keep you updated and help coordinate with contractors and inspectors.
A few things to keep in mind:
Be realistic about renovation timelines. Delays can happen.
Keep detailed records and receipts. This helps with draw requests.
Choose licensed and insured contractors. It protects you and the lender.
Understand your responsibilities. You’ll manage the renovation budget and schedule.
By partnering with experienced FHA 203k loan providers, you can avoid common pitfalls and enjoy a smoother renovation experience.
Tips for Texas Homebuyers and Real Estate Investors Using FHA 203k Loans
If you’re buying in Texas, the FHA 203k loan can be a powerful tool. Whether you’re a first-time homebuyer or a seasoned investor, here are some practical tips to make the most of it:
Work with local lenders familiar with Texas real estate. They understand market values and regulations.
Consider the property’s location and potential resale value. Renovations should add real value.
Plan your renovation budget carefully. Include a contingency for unexpected costs.
Use the loan for energy-efficient upgrades. These can increase home value and reduce utility bills.
Check local contractor licensing and insurance requirements. Texas has specific rules to protect homeowners.
Explore state and local homebuyer assistance programs. Sometimes you can combine these with FHA loans.
For investors, the FHA 203k loan can help you buy and rehab properties with less upfront cash. Just remember that the loan is intended for owner-occupied homes, so it’s best suited for those planning to live in the property.
By following these tips, you can confidently navigate the Texas housing market and turn renovation projects into profitable or comfortable homes.
Your Next Step Toward a Renovated Home
Ready to explore your options? Finding the right lender is the first step. With the right FHA 203k loan provider, you’ll get personalized guidance tailored to your goals. Whether you want to fix up a charming older home or create a custom space, this loan can make it happen.
Remember, the process might seem detailed, but it’s designed to protect you and ensure your renovation is a success. Take your time, ask questions, and lean on your lender’s expertise.
If you want to learn more or start your application, consider reaching out to trusted fha 203k renovation loan lenders who can walk you through every step.
Your dream home is waiting - with a little work and the right financing, it’s closer than you think.


Comments